Risk & Due Diligence
Credit & counterparty risk
Every sale on credit is a decision about a counterparty. We help businesses assess who they extend credit to, how much exposure they carry and how to protect it without slowing down growth.
What it is
Credit risk is the chance that a customer or partner does not pay, or pays late enough to hurt. In B2B markets it is often the largest risk a growing business carries, and it is frequently managed by habit and relationship rather than evidence.
We assess counterparties, review the credit portfolio as a whole, and design proportionate protection: credit limits and terms, credit insurance, guarantees and letters of credit, and monitoring that flags deterioration early.
Commercial and financial analysis. Not a statutory audit, legal opinion or regulated investment advice.
When it is useful
- You are extending credit to a new or fast-growing customer
- A few customers account for most of your receivables
- Payment behaviour is deteriorating
- You are considering credit insurance, or reviewing an existing policy
- You trade internationally and need security for payment
- Credit decisions rely on judgement more than data
What we assess
Scope is agreed up front; not every engagement needs every area.
Counterparty strength
Financial profile, payment behaviour and ability to perform.
Portfolio exposure
Concentration, limits and aggregate exposure across customers.
Terms & limits
Credit limits and payment terms set on evidence.
Credit insurance
Whether cover is appropriate, and how a policy fits the portfolio.
Guarantees & letters of credit
Security for payment where exposure or distance justifies it.
Monitoring
Early-warning indicators and the actions they trigger.
How we work
Map
Current exposure by customer, segment and market.
Assess
Counterparty strength and concentration, on the evidence.
Protect
Limits, terms and instruments matched to the risk.
Monitor
Indicators and routines that catch deterioration early.
Typical situations
Illustrative situations, not client case studies.
A manufacturer with one dominant customer
Concentration and credit exposure quantified, and the options for reducing them.
A distributor opening new accounts quickly
A counterparty assessment framework so limits follow evidence rather than relationship.
An exporter entering a new market
Whether letters of credit, guarantees or insurance are needed, and what each would cost.
Adviser
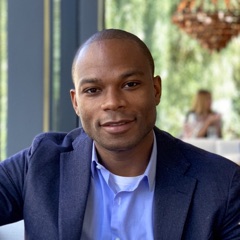
Richard Cuaresma helps businesses make better decisions where growth, credit, cash, risk and technology intersect.

Tell us who you sell to and on what terms. We will tell you where the exposure is.
Discuss your credit exposureConfidential and without obligation.